How to Choose a Roof Insurance Claim Deductible
By Editorial Team, Content Writer · November 7, 2026 · 11 min read
Last Updated: November 7, 2026
Quick Summary
A roof insurance claim deductible is the amount you pay out of pocket before your insurer covers damage, and its structure depends on your policy's type and the cause of loss. Check your declarations page to see whether you have a flat-dollar, percentage, or separate wind and hail deductible. Compare the repair estimate against that deductible before you decide to file.
- Flat-dollar deductibles are a set amount, such as $1,000 or $2,500, that applies to most covered losses.
- Percentage deductibles are calculated against your home's dwelling limit, not the repair estimate.
- A wind and hail deductible applies only when wind or hail causes the damage.
- Your out-of-pocket cost includes the deductible plus any depreciation withheld or items the adjuster left out.
- Do not sign a final payment or completion document before reviewing the full estimate.
Table of Contents
- How Roof Insurance Claim Deductibles Work
- What Is a Normal Deductible for Roof Replacement?
- Comparing Roof Deductible Options: Flat, Percentage, and Wind-Hail
- Roof Replacement Insurance Claim Out-of-Pocket Cost
- Roof Insurance Claim Estimate Supplement: Catching What the Deductible Hides
- Deciding Whether a Roof Claim Is Worth Filing Against Your Deductible
- Checking Your Deductible Before You Start Your Next Roof Claim
- Frequently Asked Questions
How Roof Insurance Claim Deductibles Work
A roof insurance claim deductible is the amount you pay out of pocket before your insurer pays for covered roof damage. Understanding the deductible is the first step to a fair claim.
Most homeowners think of the deductible as a single fixed bill. In practice, it changes with the type of policy and the cause of the damage. Read your declarations page before you file, because the wording there controls the outcome.
- Flat-dollar deductible: A set amount, such as $1,000 or $2,500, that applies to most covered losses.
- Percentage deductible: A share of your home's insured value, often used for named storms or hail.
- Separate wind and hail deductible: A different amount that applies only to wind or hail damage.
Watch out: A claim can be approved and still pay little if the deductible is higher than the repair cost. Always compare the estimate against the deductible before you decide to file.
What Is a Normal Deductible for Roof Replacement?
A typical deductible for a roof replacement claim is a flat amount between $500 and $2,500 for most standard policies. Percentage-based wind and hail deductibles often run 1% to 5% of your home's insured value, which can mean several thousand dollars. Your policy declarations page shows which deductible applies to your roof.
Many homeowners assume the lowest deductible is always best. A lower deductible raises your premium, so the right choice depends on your budget and how likely you are to file.
Comparing Roof Deductible Options: Flat, Percentage, and Wind-Hail
Deductible structure decides how much of a roof claim you actually collect, so it pays to read the policy language rather than assume a single number applies. The three structures below behave very differently when a claim is filed.
| Deductible Type | What It Is Calculated Against | Typical Range | Where to Find It | Best For | Main Drawback |
|---|---|---|---|---|---|
| Flat-dollar | A fixed dollar amount stated on the declarations page | $500 to $2,500 on many standard policies | Declarations page, "Deductible" line | Predictable out-of-pocket cost | Can exceed the cost of small repairs |
| Percentage | A percentage of the dwelling (Coverage A) limit, not the repair estimate | 1% to 5% on many policies | Declarations page and the deductible endorsement | Homes with high replacement cost where a flat deductible feels small | Grows with the insured value of the home |
| Wind and hail | A separate deductible, often percentage-based, triggered only by wind or hail | 1% to 5% of dwelling coverage, sometimes higher in storm regions | A named-storm or wind/hail deductible endorsement | Coastal and hail-prone areas | Applies even to modest storm damage |
Flat-dollar deductibles. A flat deductible is the simplest structure: a stated amount, such as $1,000 or $2,500, comes off the top of every covered loss. The number does not change with the size of the repair, so a $1,000 deductible on a $12,000 roof replacement leaves $11,000 of covered loss before depreciation and other adjustments. The trade-off is that a flat deductible can wipe out a small repair entirely, a $900 repair with a $1,000 deductible pays nothing.
Percentage deductibles. A percentage deductible is calculated against the dwelling limit on the policy, not against the contractor's estimate. Read the declarations page and the deductible endorsement to confirm the base the percentage applies to. That distinction trips up many homeowners, who assume the percentage applies to the claim amount. Read the declarations page and the deductible endorsement together, because the endorsement defines what the percentage is calculated against and which perils trigger it.
Wind and hail deductibles. A separate wind and hail deductible applies only when the damage is caused by wind or hail. The same policy may carry a $2,500 flat deductible for fire or falling-object damage and a 2% wind/hail deductible for a storm claim. Confirm which peril caused the damage and which deductible the policy assigns to that peril before you assume a payout.
How the structures interact. A single policy can carry more than one deductible, and the one that applies depends on the cause of loss. A fallen tree might trigger the flat deductible, while hail on the same roof triggers the wind/hail deductible. The declarations page and endorsements control, so read them side by side and note which deductible is tied to which peril.
Watch out: A percentage deductible is calculated against the dwelling limit, not the repair estimate, so a 2% deductible on a $400,000 home is $8,000 even when the roof estimate is far smaller. Confirm the calculation base in the endorsement before you budget for a claim.
Roof Replacement Insurance Claim Out-of-Pocket Cost
Your out-of-pocket cost equals the deductible plus any amount the insurer does not pay. This can include depreciation withheld under actual cash value coverage or line items the adjuster left out.
- Deductible paid to start the work
- Depreciation withheld until repairs are complete
- Items missing from the adjuster's estimate
Watch out: Do not sign a final payment or completion document before you have reviewed the full estimate, because it can close the claim.
Roof Insurance Claim Estimate Supplement: Catching What the Deductible Hides
A supplement is a request to add line items the original estimate left out. Common examples include starter strips, drip edge, steep-roof charges, and permit fees. These additions can raise the payout enough to offset part of the deductible.
Compare each line of the adjuster's estimate against your measurements and the manufacturer's installation requirements. ScopeProof cross-references adjuster estimates with measurement reports and drafts supplements with cited requirements, so missing items are easier to defend. Find out if an estimate review service is worth it for your claim, including what it checks and what it costs, on our estimate review page.
Deciding Whether a Roof Claim Is Worth Filing Against Your Deductible
Filing a roof claim is a math problem before it is a paperwork problem. The question is whether the covered payout, after the deductible and depreciation, is large enough to justify the claim and any effect on your premium or claims history. A simple comparison gets you most of the way there.
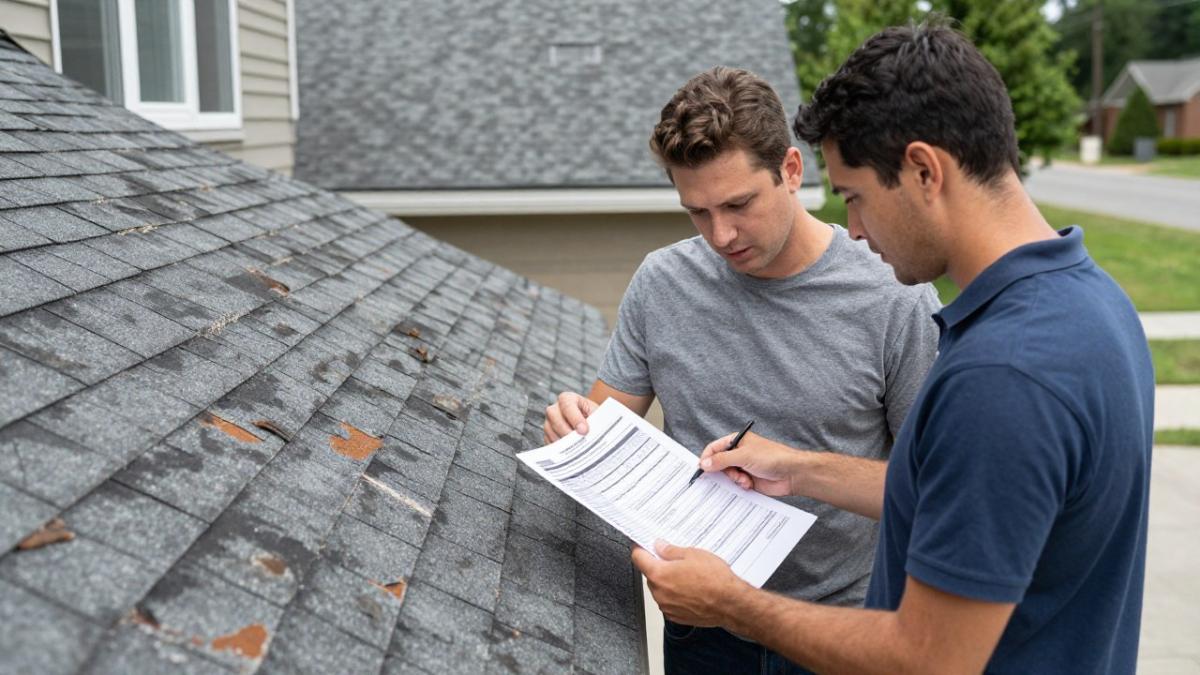
Step 1: Estimate the covered repair cost. Get a written contractor estimate that reflects the full scope, tear-off, underlayment, shingles, flashing, drip edge, ridge vent, and labor. Use the replacement cost figure, not a discounted cash price, because that is what the insurer will compare against.
Step 2: Identify the deductible that applies to the peril. Confirm from the declarations page and endorsements whether the loss triggers the flat deductible or a separate wind/hail deductible. For a percentage deductible, multiply the percentage by the dwelling limit, not by the repair estimate.
Step 3: Subtract the deductible from the covered repair cost. This is the covered loss before depreciation. If the result is zero or negative, the claim pays nothing and filing is usually pointless.
Step 4: Account for depreciation if the policy pays actual cash value. Under actual cash value coverage, the insurer withholds depreciation until repairs are complete, and you recover it only by submitting proof of completed work. You can follow the steps to recover withheld depreciation and lift your payout toward full replacement cost. On an older roof, withheld depreciation can be a large share of the estimate, which shrinks the initial check and raises your short-term out-of-pocket cost even though the final payout may be similar.
Step 5: Compare the net payout to your out-of-pocket exposure and your claims history. A claim that nets a few hundred dollars may not be worth the effect on your premium at renewal or your claims record. A claim that nets several thousand dollars usually is.
Questions to answer before you file:
- Is the replacement cost estimate well above the deductible that applies to this peril?
- Does the damage fall under wind, hail, or another covered peril, and which deductible does the policy assign to it?
- Is the policy paying replacement cost or actual cash value, and how much depreciation will be withheld?
- Will a claim affect your premium at renewal or your claims history?
- Have you documented the damage with photos, dates, and a written contractor estimate?
Filing on a small repair can leave little after the deductible while still affecting renewal premiums, so running the numbers first helps.
Watch out: Do not file before you know which deductible applies. A percentage wind/hail deductible can exceed the net payout on a modest repair, turning a claim into a net loss once premium effects are counted.
Checking Your Deductible Before You Start Your Next Roof Claim
Review your declarations page, confirm which deductible applies to roof damage, and get a written estimate before you sign anything. Keep photos and records of the damage, and ask the adjuster to explain every line item. For the full sequence from damage documentation through final payment, see roofing claim management from start to finish. Taking these steps before work begins makes it easier to choose the right deductible strategy.
Frequently Asked Questions
What is a normal deductible for roof replacement?
Most homeowners insurance policies carry a flat deductible in the range of $500 to $2,500, though many policies set a percentage deductible for wind and hail, commonly 1% to 5% of the dwelling coverage limit. Your declarations page shows which type applies and the exact figure. Because the deductible is subtracted from the claim payout, a roof replacement only pays out the amount above it. Check your own policy wording rather than relying on a typical range, since carriers and states set these terms differently.
How do I calculate my out-of-pocket cost for a roof claim?
Start with the approved replacement or repair estimate, then subtract the deductible that applies to the cause of loss. For a percentage wind-hail deductible, multiply your dwelling coverage limit by the percentage to get the dollar amount. Next, account for depreciation if your policy pays actual cash value first, since recoverable depreciation may be released only after repairs are completed. Any amount the insurer does not approve, including line items disputed in an estimate, may also fall to you.
Can I choose a different deductible for a roof insurance claim?
Sometimes. Many carriers let you select a higher deductible at policy renewal in exchange for a lower premium, but changing it after a loss usually is not an option. Wind and hail deductibles are often set separately from your all-peril deductible, so check which one your declarations page assigns to roof damage from storms. Ask your agent before filing, because the deductible in force on the date of loss generally controls.
Should I file a roof claim if the repair cost is close to my deductible?
Usually not, if the approved payout would be small after subtracting your deductible. Filing can still raise your claims history and affect future premiums, so compare the net payout against the likely premium impact. If the damage is extensive or the estimate is likely to rise through a supplement, the calculation may change. Documenting damage with dated photos and a contractor inspection helps you make that decision with real numbers.

- roof insurance claim deductible
- roof insurance claim deductible options
- what is a normal deductible for roof replacement
- roof replacement insurance claim out-of-pocket cost